
If you had to name one Korean-listed AI bellwether, a growing number of local investors would say SK hynix first. 😮
The stock has that kind of momentum — HBM, AI servers, the memory super-cycle: every thread seems to run through this one company.
But the stronger the name, the harder the decision. You can see the earnings are overwhelming; what you cannot easily judge is whether today is a reasonable entry or an overheated one.

Pairs well with this article
Monitor Light Bar That Cuts Eye Strain
💬 One-line tip: late-night chart and filing sessions get noticeably kinder once you fix the ambient lighting alone.
✨ Key takeaways
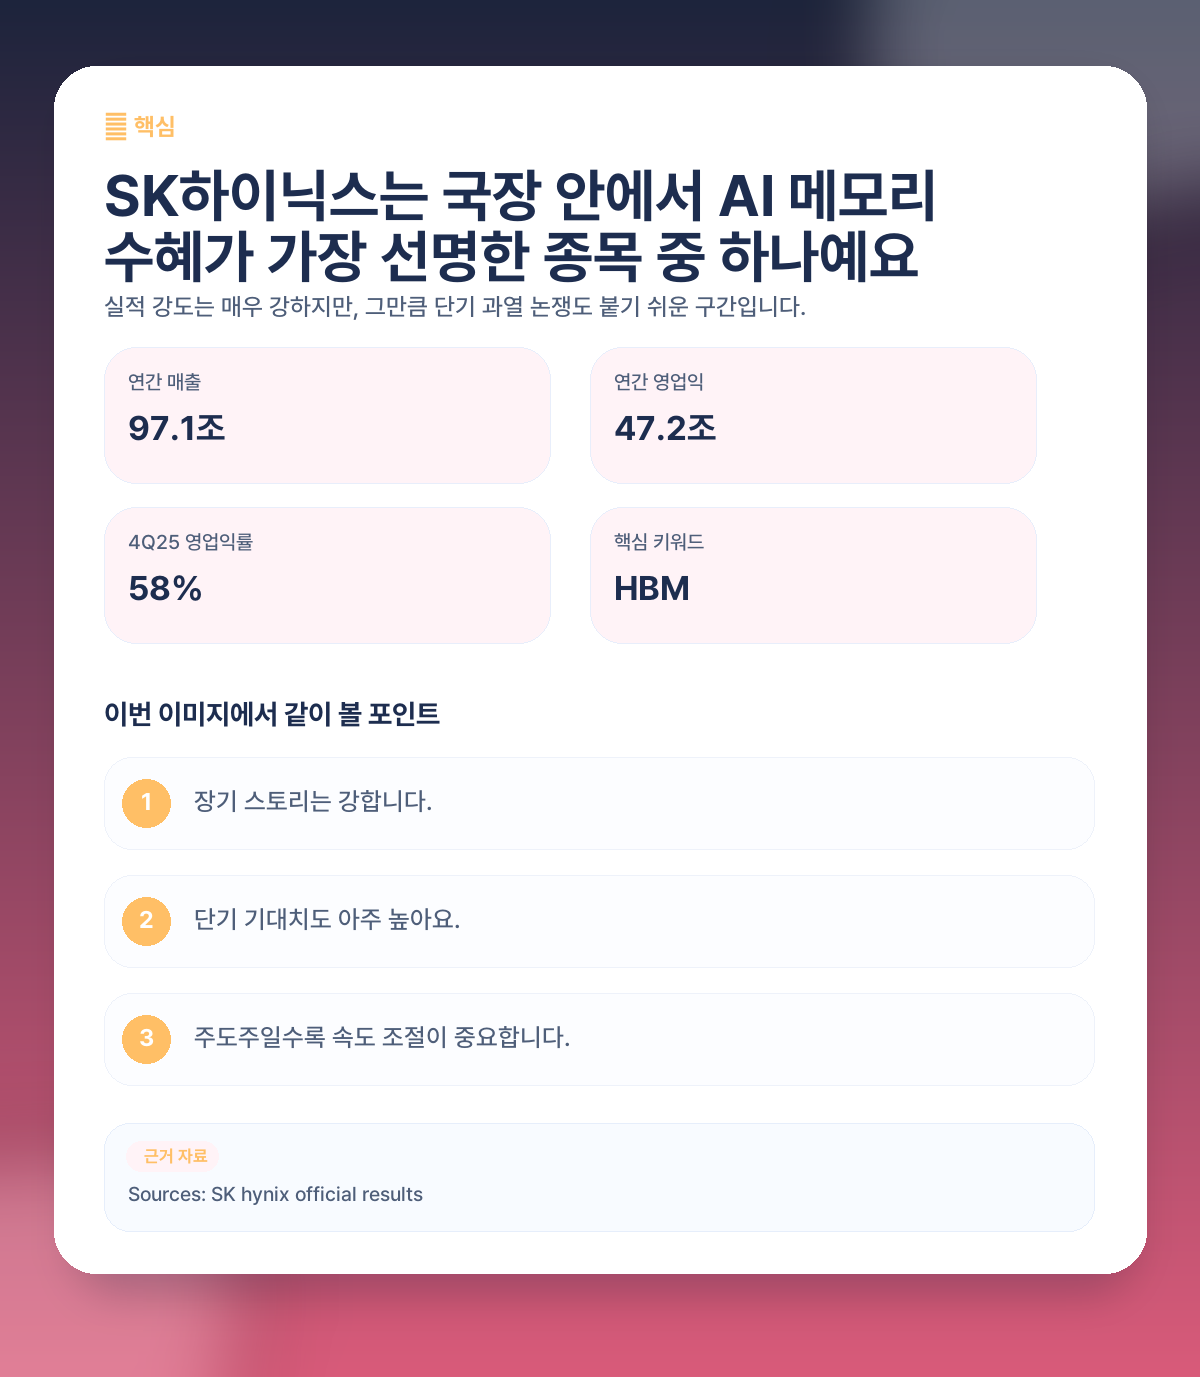
Bottom line: within the Korean market, SK hynix is about as direct a play on the AI-memory wave as it gets. The numbers are strong and the company’s own messaging is confident.
But a great stock and an easy entry are two different things. The long-term growth logic is powerful; at the same time, this is a name where the overheating debate flares up easily in the short run.
- Long-term strength: HBM and AI-memory demand map straight onto its results.
- Short-term strain: elevated expectations mean the volatility can expand.
- Practical point: watch the cycle, the flows, and how much expectation you are paying for.
📈 Where SK hynix actually stands right now
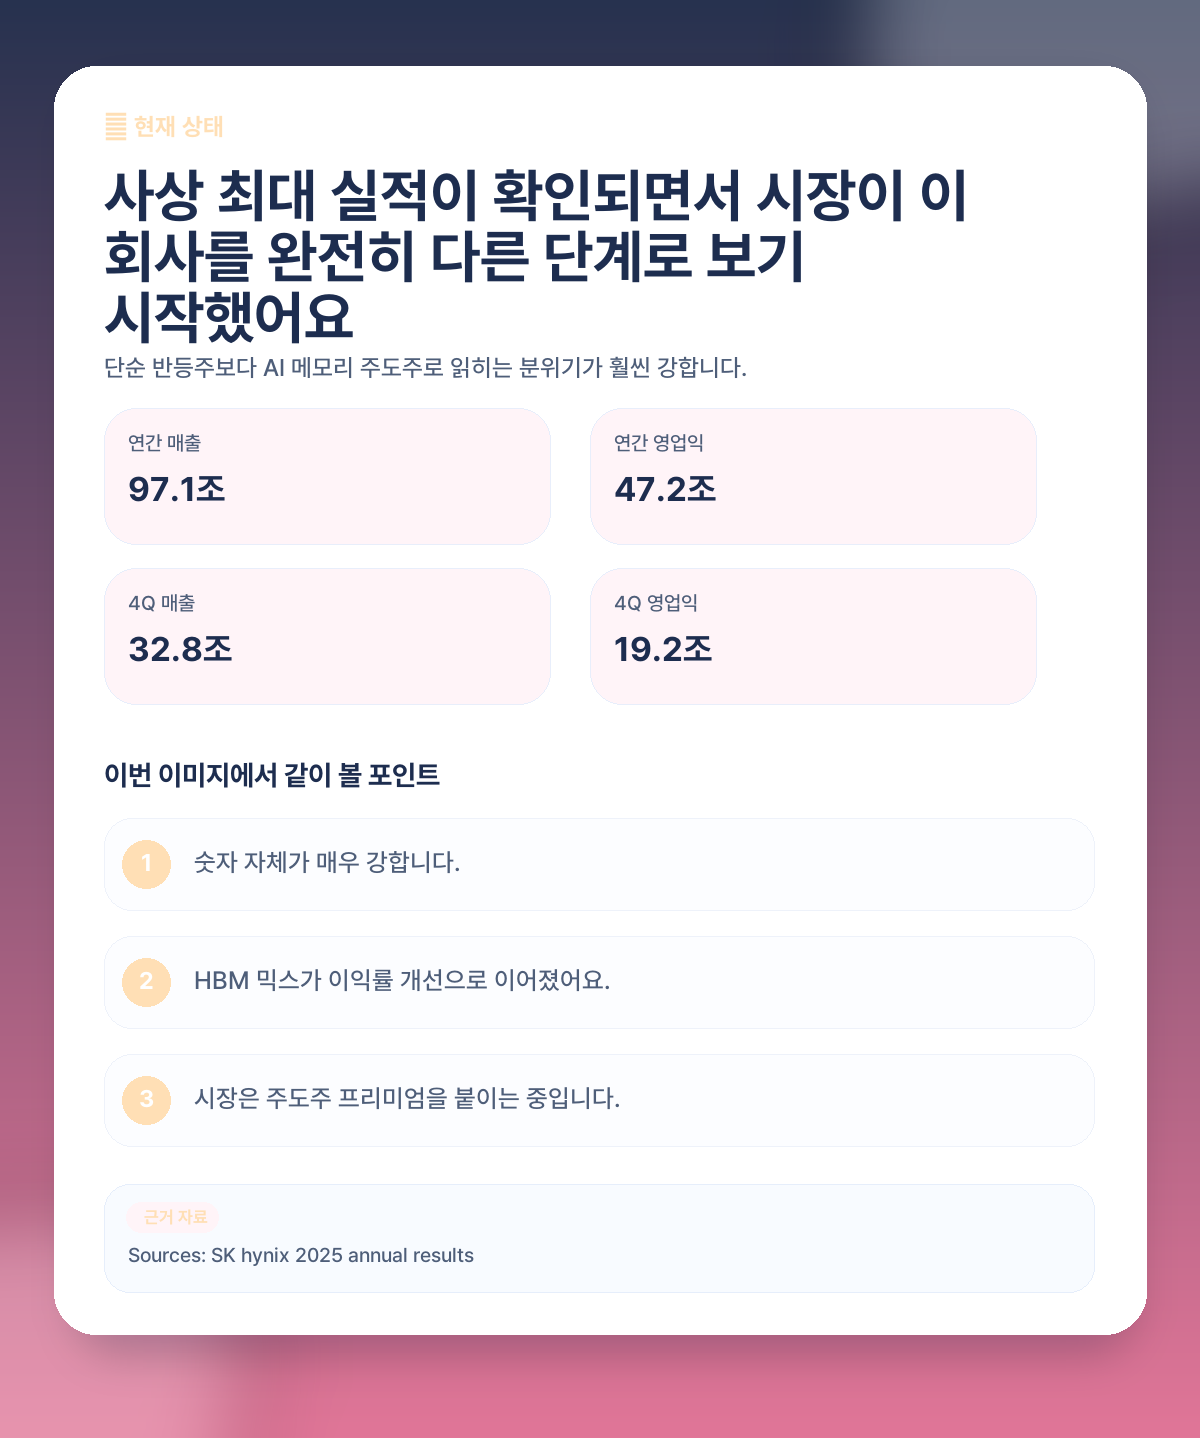
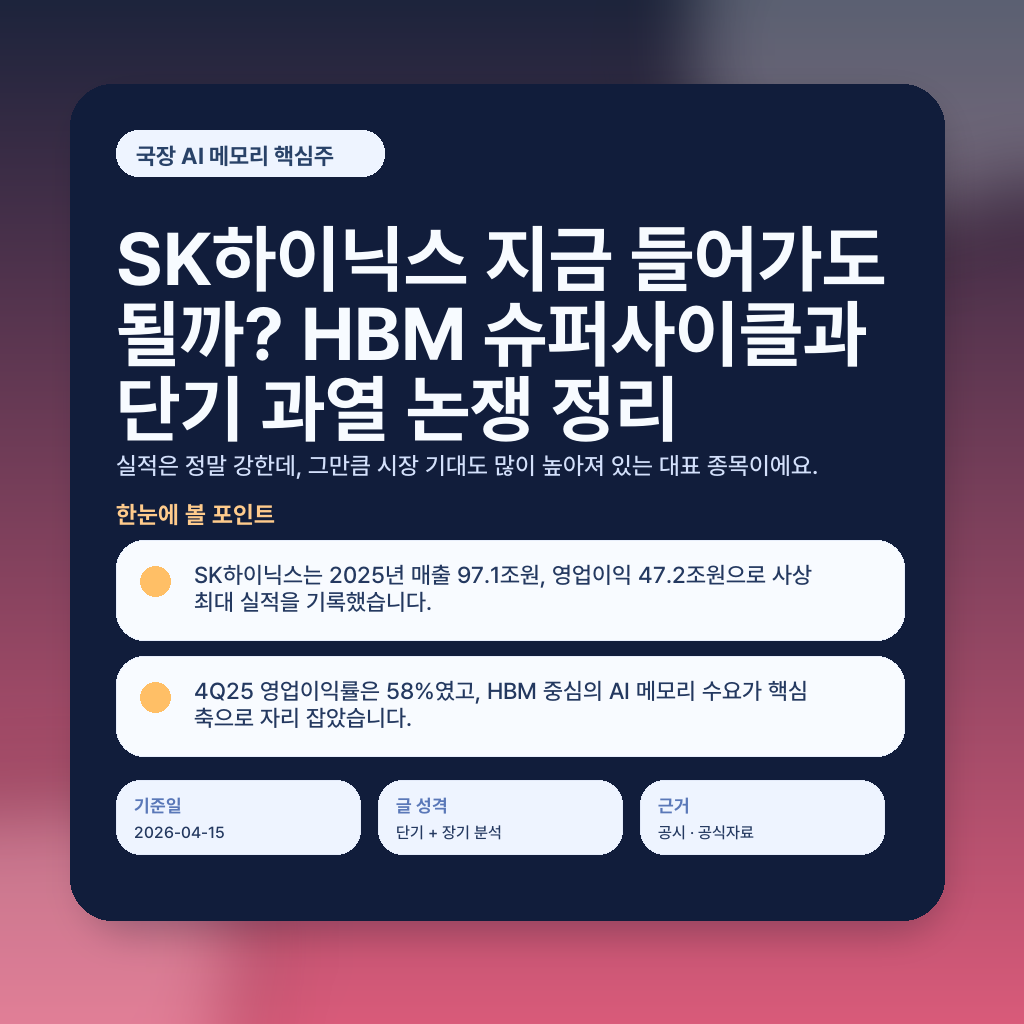
Per the company’s official release, FY2025 revenue was KRW 97.1467 trillion with operating profit of KRW 47.2063 trillion. The numbers were strong enough for SK hynix to call it a record year in its own words — and Q4 alone delivered KRW 32.8267 trillion in revenue and KRW 19.1696 trillion in operating profit.
The Q4 operating margin of 58% is the detail that explains why the market treats this company as special. This is not a plain memory recovery; it is an AI-memory mix shift converting directly into profitability.
So the better way to read SK hynix today is not “a memory-rebound beneficiary” but “the AI-memory leader.”
- Both the annual and quarterly prints are confirmed strong.
- The HBM mix flowed straight into margin expansion.
- The market already prices it as a leader, not a laggard rebound.
🚀 Why the HBM super-cycle talk keeps coming back
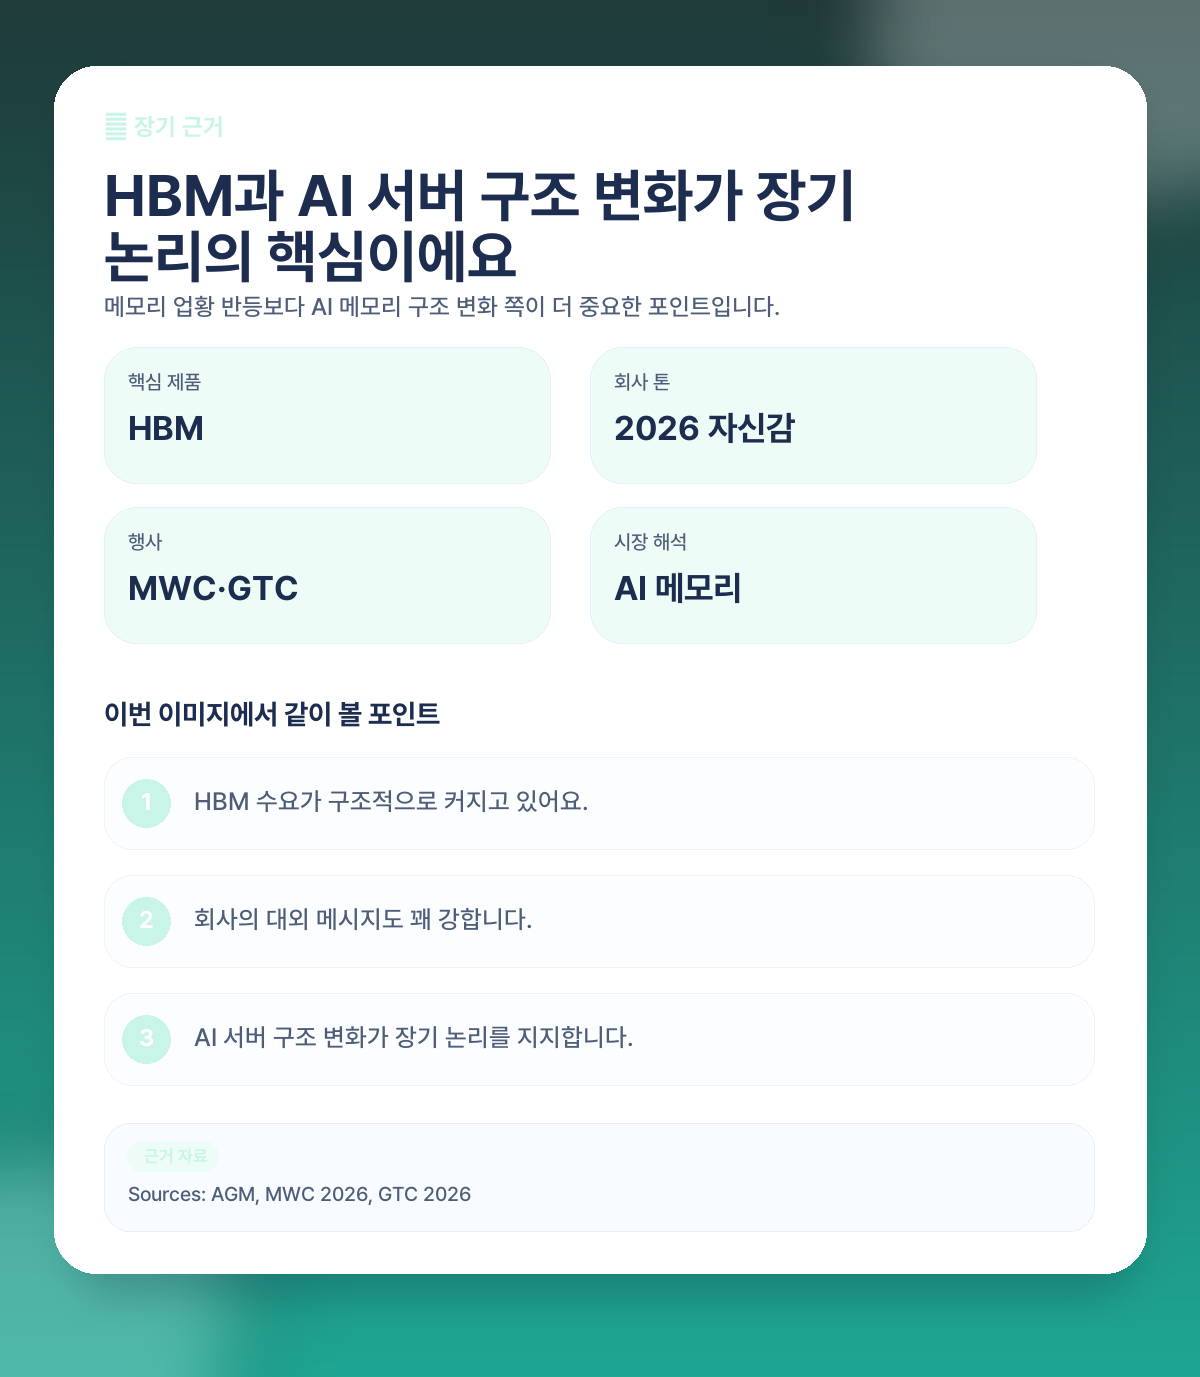
What makes SK hynix attractive long term is less a cyclical upturn than a structural shift. As AI servers and high-bandwidth memory demand grow, the strategic position of HBM suppliers rises sharply.
Bolstered by its record 2025, the company struck a confident tone for 2026 at its AGM and external events, actively showcasing its AI-memory portfolio at venues such as MWC and GTC.
In other words, this is not simply a memory-price rebound cycle — memory’s strategic weight inside the AI ecosystem has moved up a level, and that is the heart of the long-term case.
- Expanding HBM demand sits at the center of the growth thesis.
- The company’s external messaging is emphatic.
- The structural shift in AI servers underwrites the long view.
Pairs well with this article
Laptop Stand That Makes Long Sessions Easier
💬 One-line tip: raising your eye line just a little cuts intraday fatigue more than you would expect.
⚠️ So why the overheating debate in the near term?
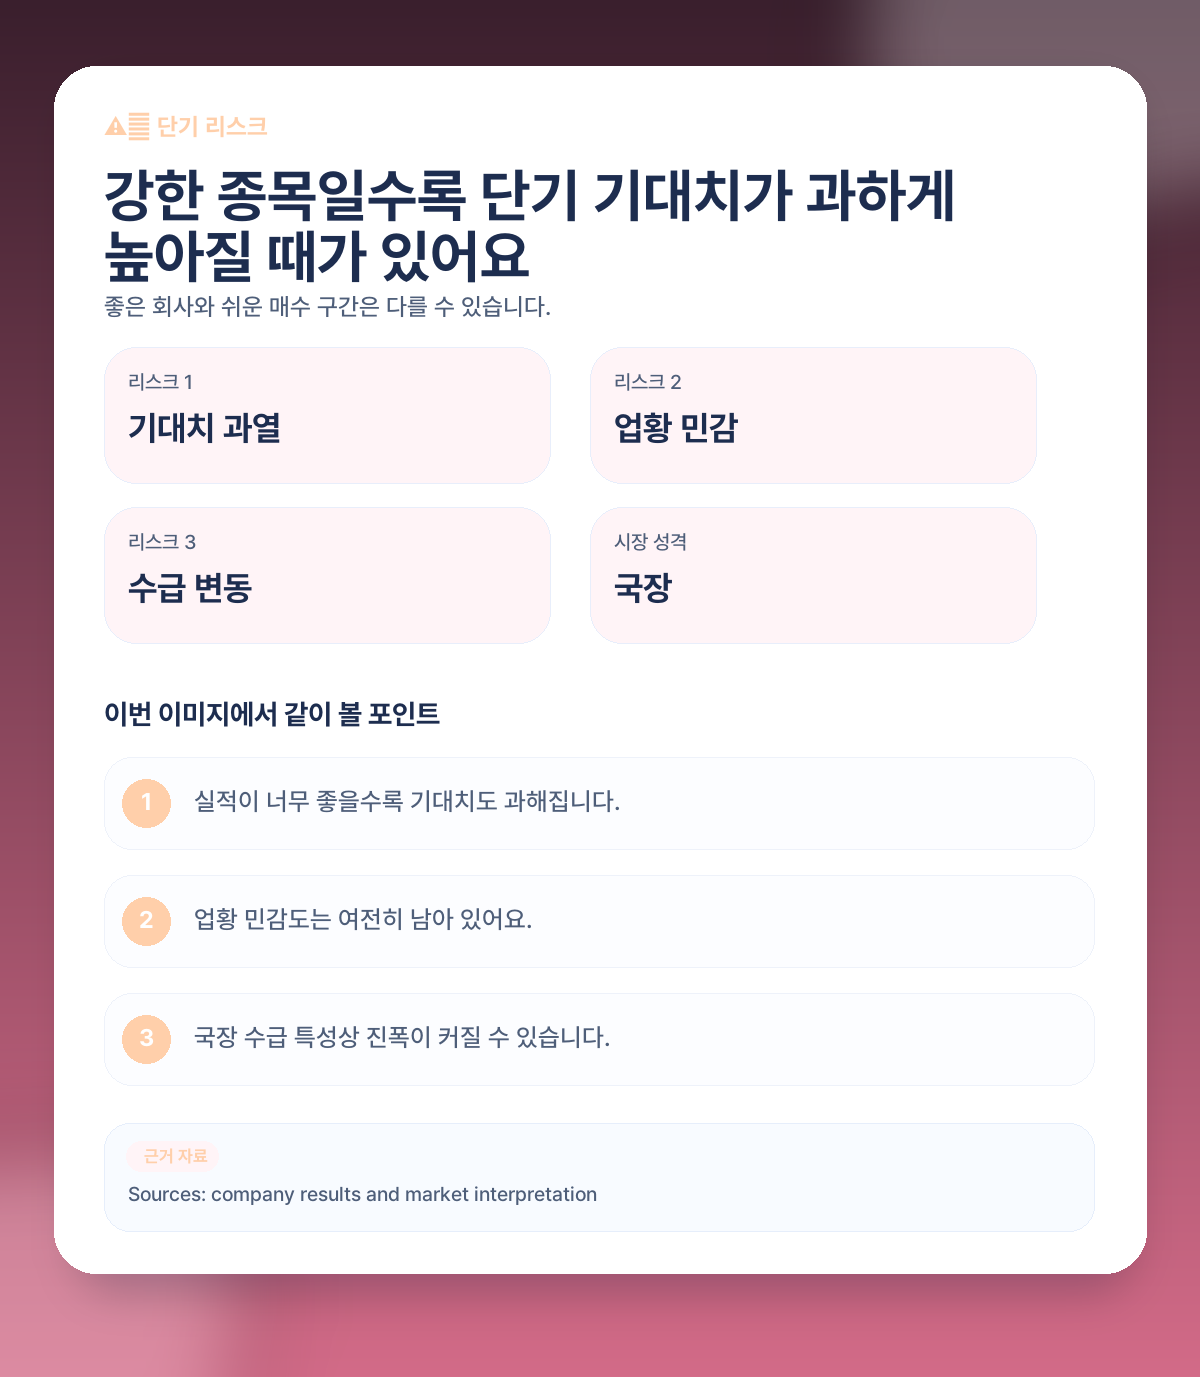
First: expectations. SK hynix has already printed numbers this strong, so the market’s question shifts from “is it good?” to “how long can good like this last?”
Second: cycle sensitivity. However strong HBM is, semiconductors remain sensitive to the industry cycle, supply-demand, and customers’ investment direction. The more expectation a stock concentrates, the bigger its reaction to small news.
Third: the volatility style of the Korean market. KOSDAQ/KOSPI names react fast to flows and sentiment, so even excellent stocks often swing in wider ranges than expected.
- The better the earnings, the higher the bar the market sets next.
- The longer HBM strength runs, the more fatigue can build alongside it.
- Korean-market flow dynamics can amplify the swings.
🧭 The realistic stance on SK hynix today
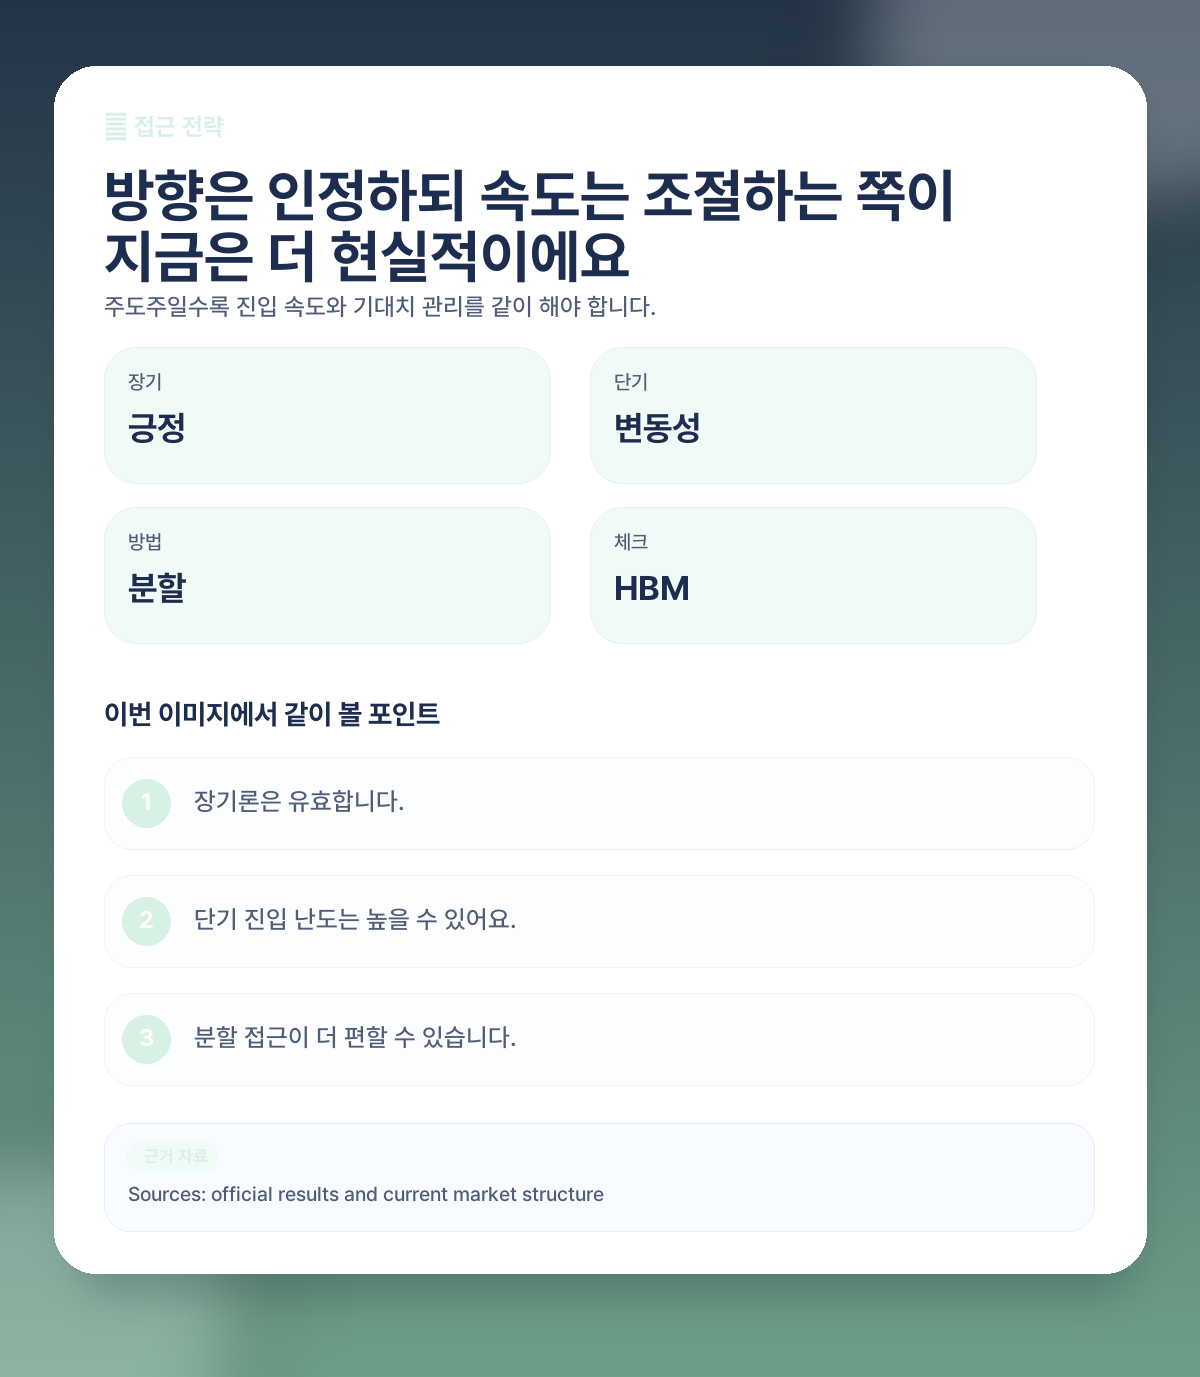
Long term, it remains one of the clearest AI-memory winners. But loading up in one shot during a run this strong makes any pullback genuinely hard to hold through.
So for this stock, the issue is not denying the direction — it is managing the speed. Even more so precisely because it is the market leader.
With the cycle and the earnings axis this strong, the realistic stance leans on staged entries on dips and active expectation management.
- The long story is strong; the short-term entry pace still needs control.
- Leader or not, tranches beat one big bet.
- Manage the earnings- and news-window volatility separately.
🗓️ Numbers and dates to watch together
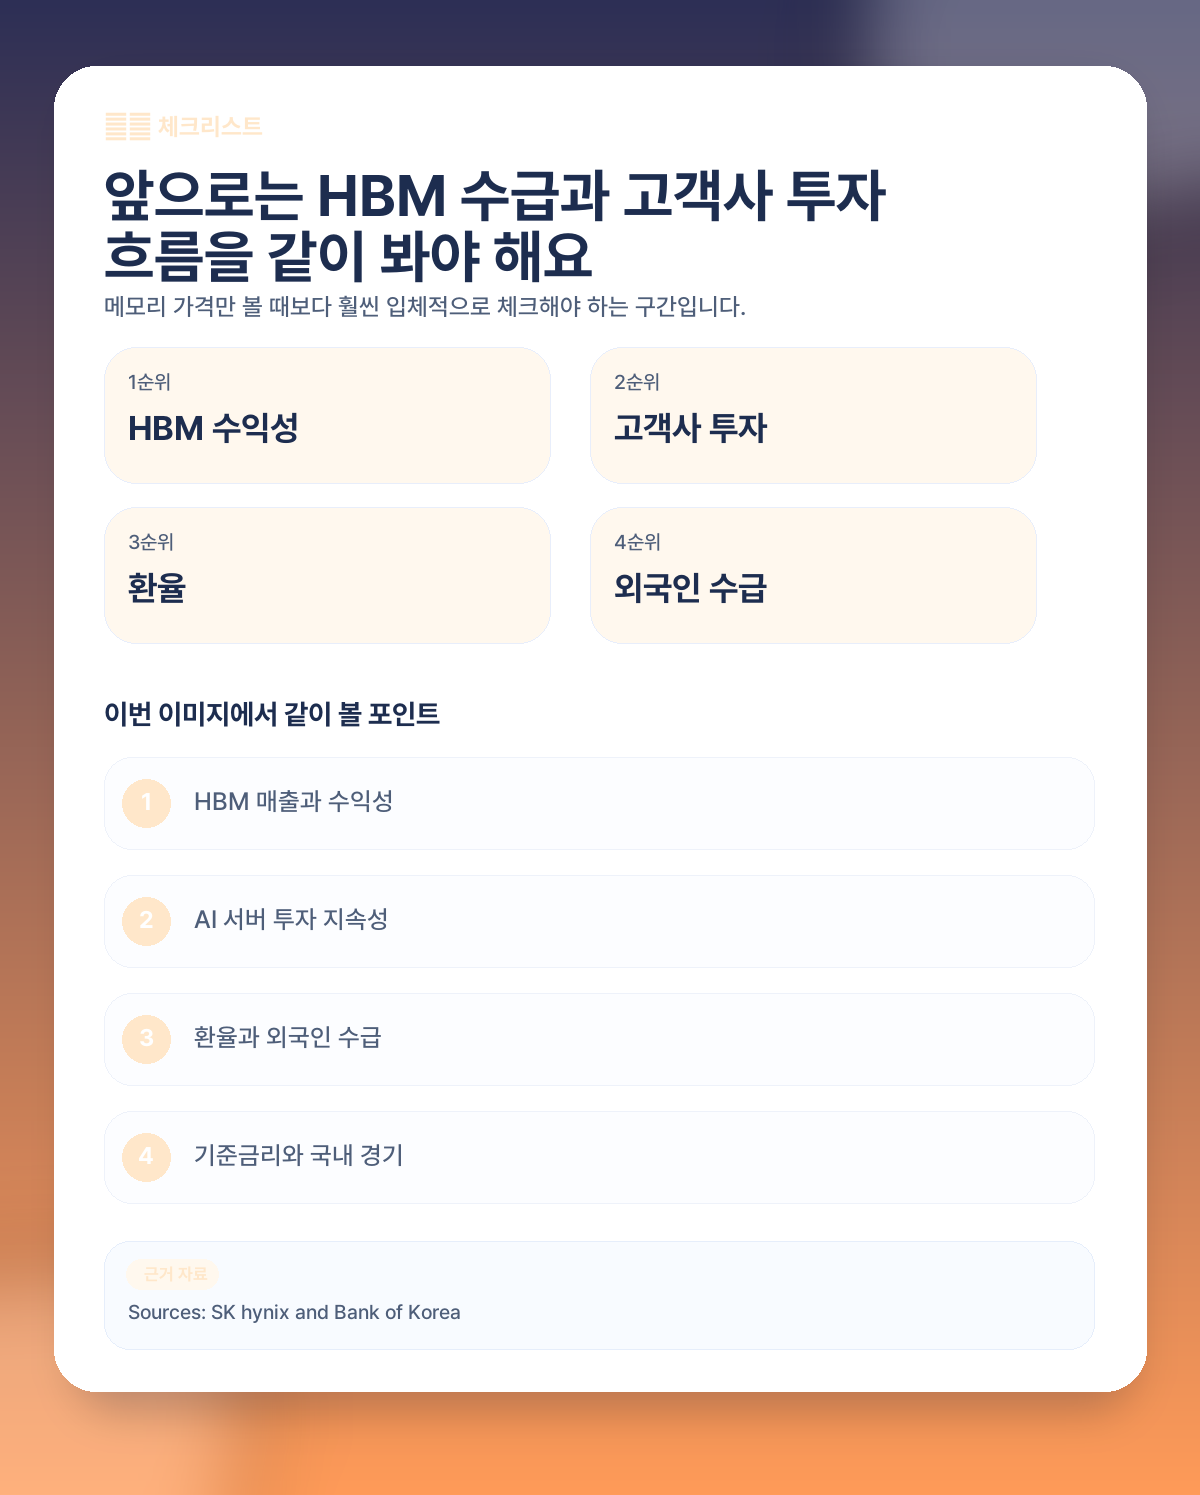
Going forward, HBM supply-demand and customers’ AI investment tell you more about SK hynix than spot memory prices ever will.
Also keep the Bank of Korea’s policy rate, the domestic economy, the won, and foreign flows in view — that combination is what makes the lived trend legible.
- Next quarter’s HBM revenue and profitability
- Customers’ AI server investment plans
- The won exchange rate and foreign investor flows
- The Bank of Korea’s rate path and the domestic economy
Pairs well with this article
Wireless Mouse Built for Notes and Chart Switching
💬 One-line tip: if you live between charts, notes, and browser tabs, the right basic tool is felt more than you’d think.
❓ FAQ
❓ Is it already too late for SK hynix?
In the short run it can feel that way. But the long-term story is still strong, so it is less “too late” than “slow down the pace of entry.”
❓ Would SK hynix be hit first if the HBM cycle turns?
Relatively speaking, yes — its exposure is direct. That is exactly why HBM demand durability and customers’ investment direction need constant checking.
❓ Is it the more aggressive pick versus Samsung Electronics?
Generally yes. SK hynix rides the HBM wave more directly, so it offers more torque — and correspondingly more volatility.
❓ Does being Korean-listed mean bigger swings?
Yes. Flows and sentiment move fast in the domestic market, so even quality names can swing hard in the short term.
🔎 Public sources referenced