
Hanwha Aerospace reads less like a plain defense stock now and more like the flagship of Korea’s defense super-cycle with a space story layered on top. 🚀
Which is exactly why investors agonize over it. Orders and earnings expectations look strong — but how much of that story has the market already bought?
As of April 15, 2026, this piece leans on official IR materials to lay out where Hanwha Aerospace stands, why long-term expectations run so high, and what to watch warily near term.

Pairs well with this article
Monitor Light Bar That Cuts Eye Strain
💬 One-line tip: late-night chart and filing sessions get noticeably kinder once you fix the ambient lighting alone.
✨ Key takeaways
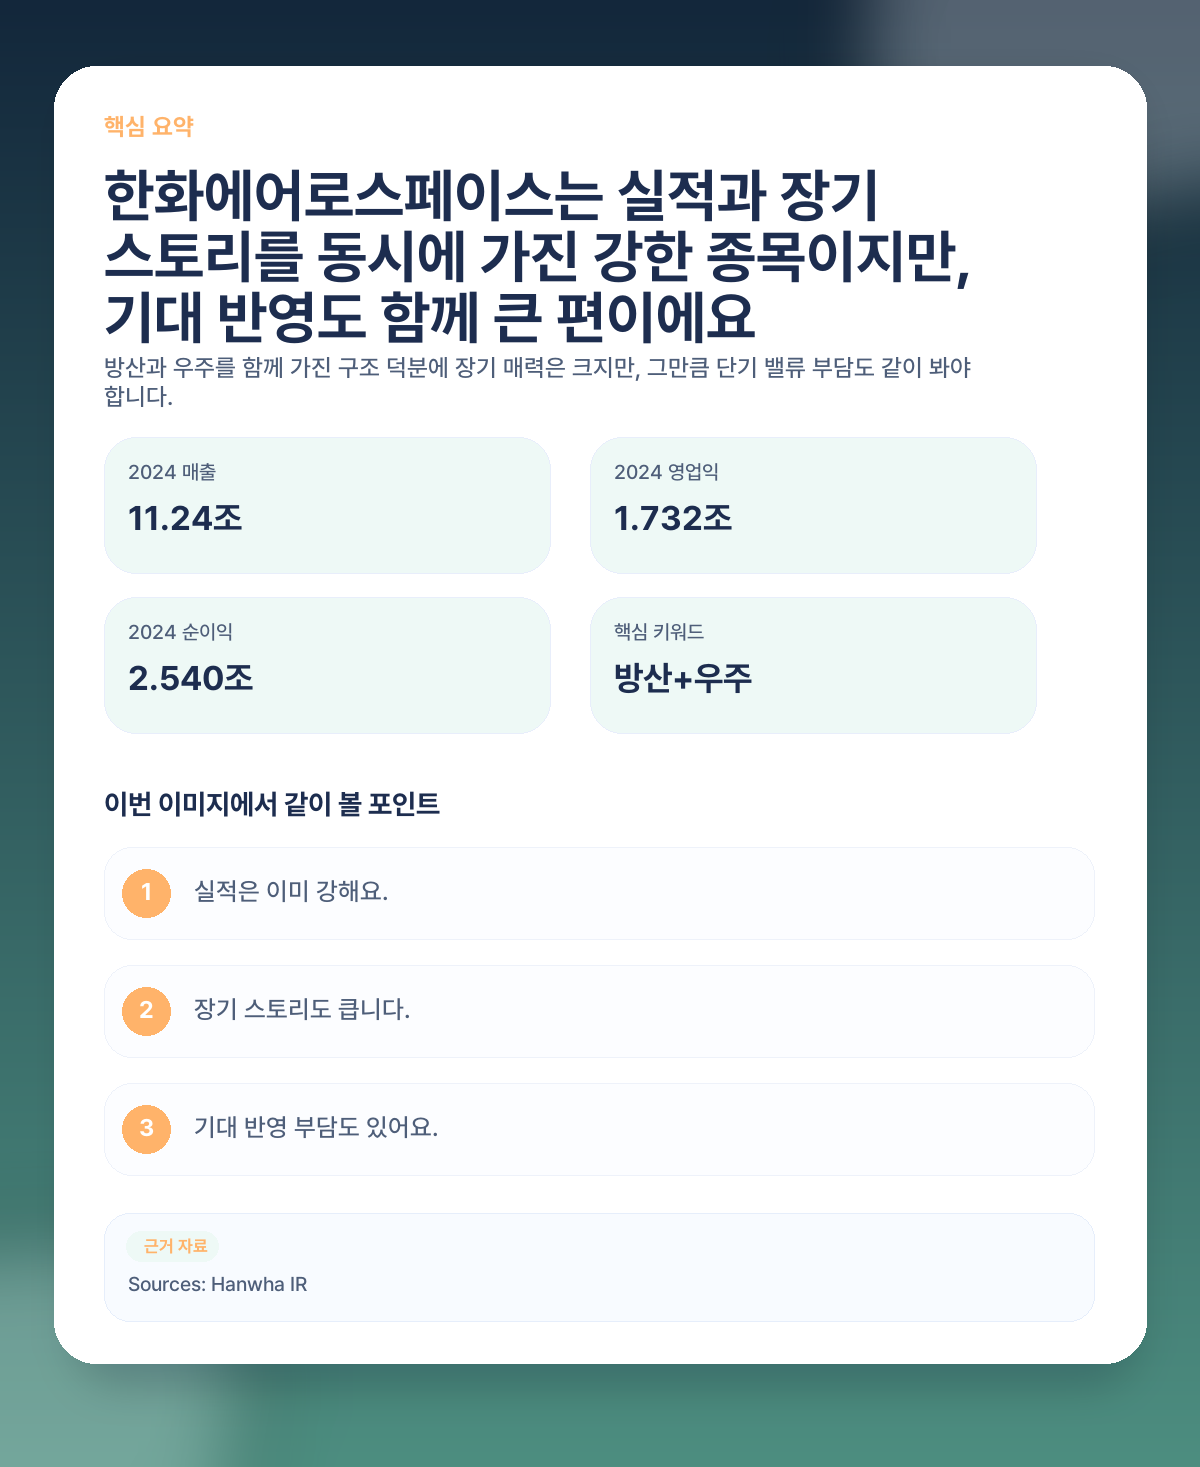
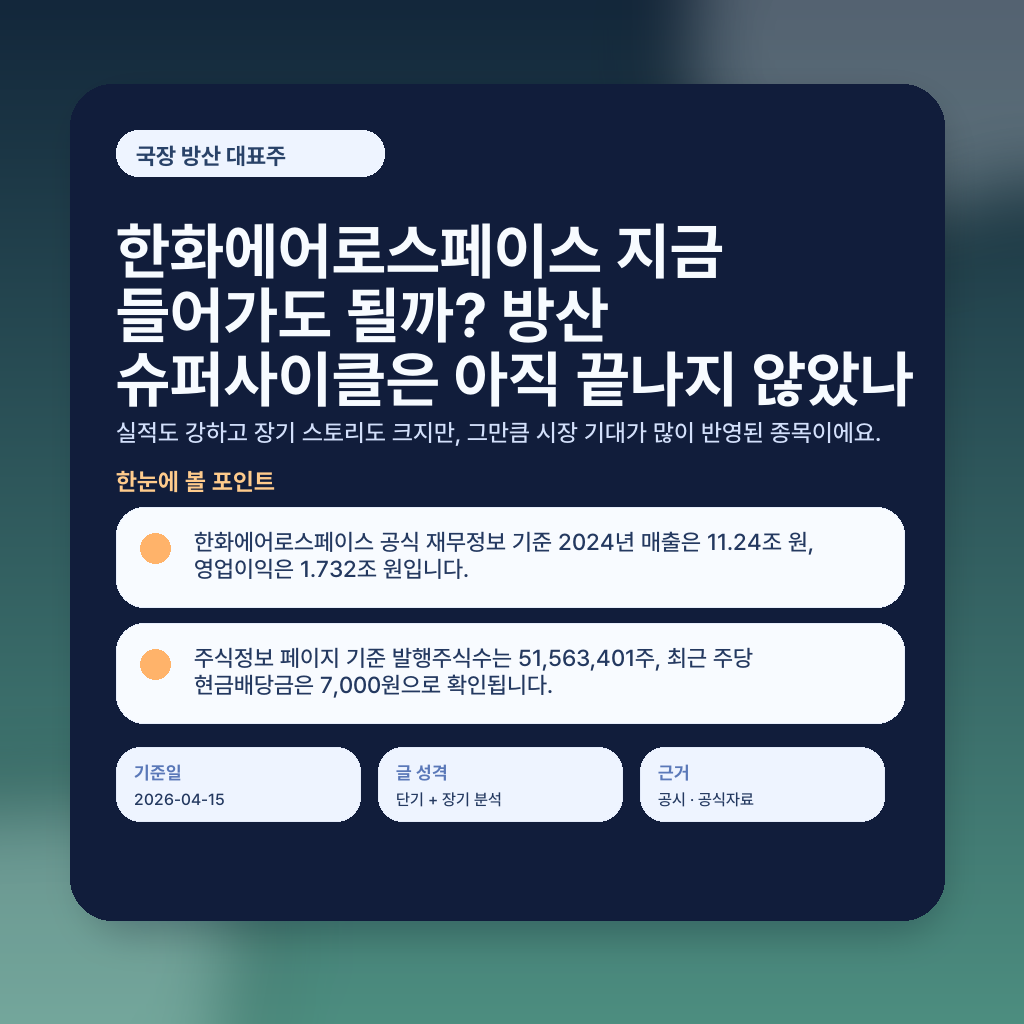
Up front: Hanwha Aerospace is a rare Korean name with both earnings and a story. The official financial disclosures show 2024 consolidated revenue of KRW 11.24 trillion, operating profit of KRW 1.732 trillion and net profit of KRW 2.540 trillion — the numbers are genuinely strong.
The relevant question now is not “is it a good company” but “how much of that goodness is already priced in.” With a defense super-cycle and a space narrative stacked together, the richer the expectations, the wider the swings.
- Long-term strength: two engines — defense and space.
- Short-term strain: the higher the expectations, the heavier the valuation burden.
- Practical point: read order momentum and reported earnings together.
📊 Where Hanwha Aerospace stands right now
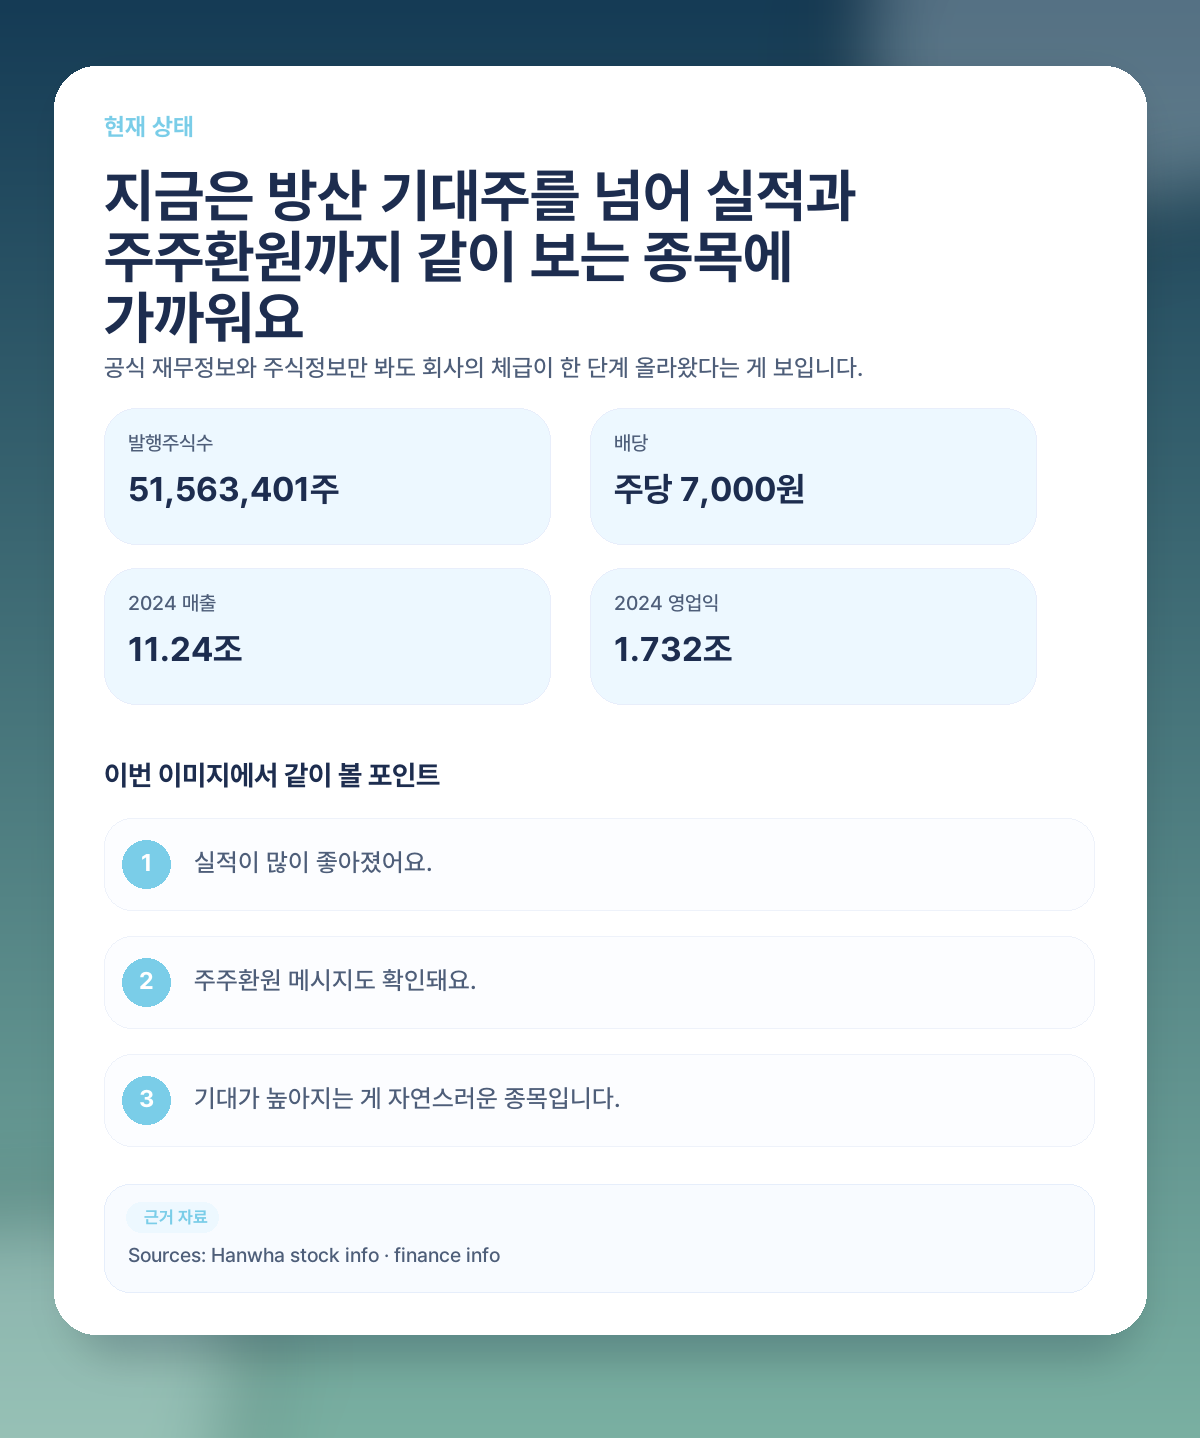
The company’s official financial information page shows 2024 consolidated revenue of KRW 11.24 trillion, operating profit of KRW 1.732 trillion and net profit of KRW 2.540 trillion. On the numbers alone, the earnings level has moved up a tier from the old regime.
Its official stock information page lists 51,563,401 shares outstanding and a recent cash dividend of KRW 7,000 per share, with a stated commitment to continue shareholder-return policies including buybacks, cancellations and cash dividends.
So Hanwha Aerospace is no longer priced as a “defense hope” — it has graduated to a name read through actual earnings plus shareholder returns.
- Earnings are already up strongly.
- The shareholder-return message is on the official page.
- Rising market expectations are the natural consequence.
🧠 Why the long-term camp stays enthusiastic
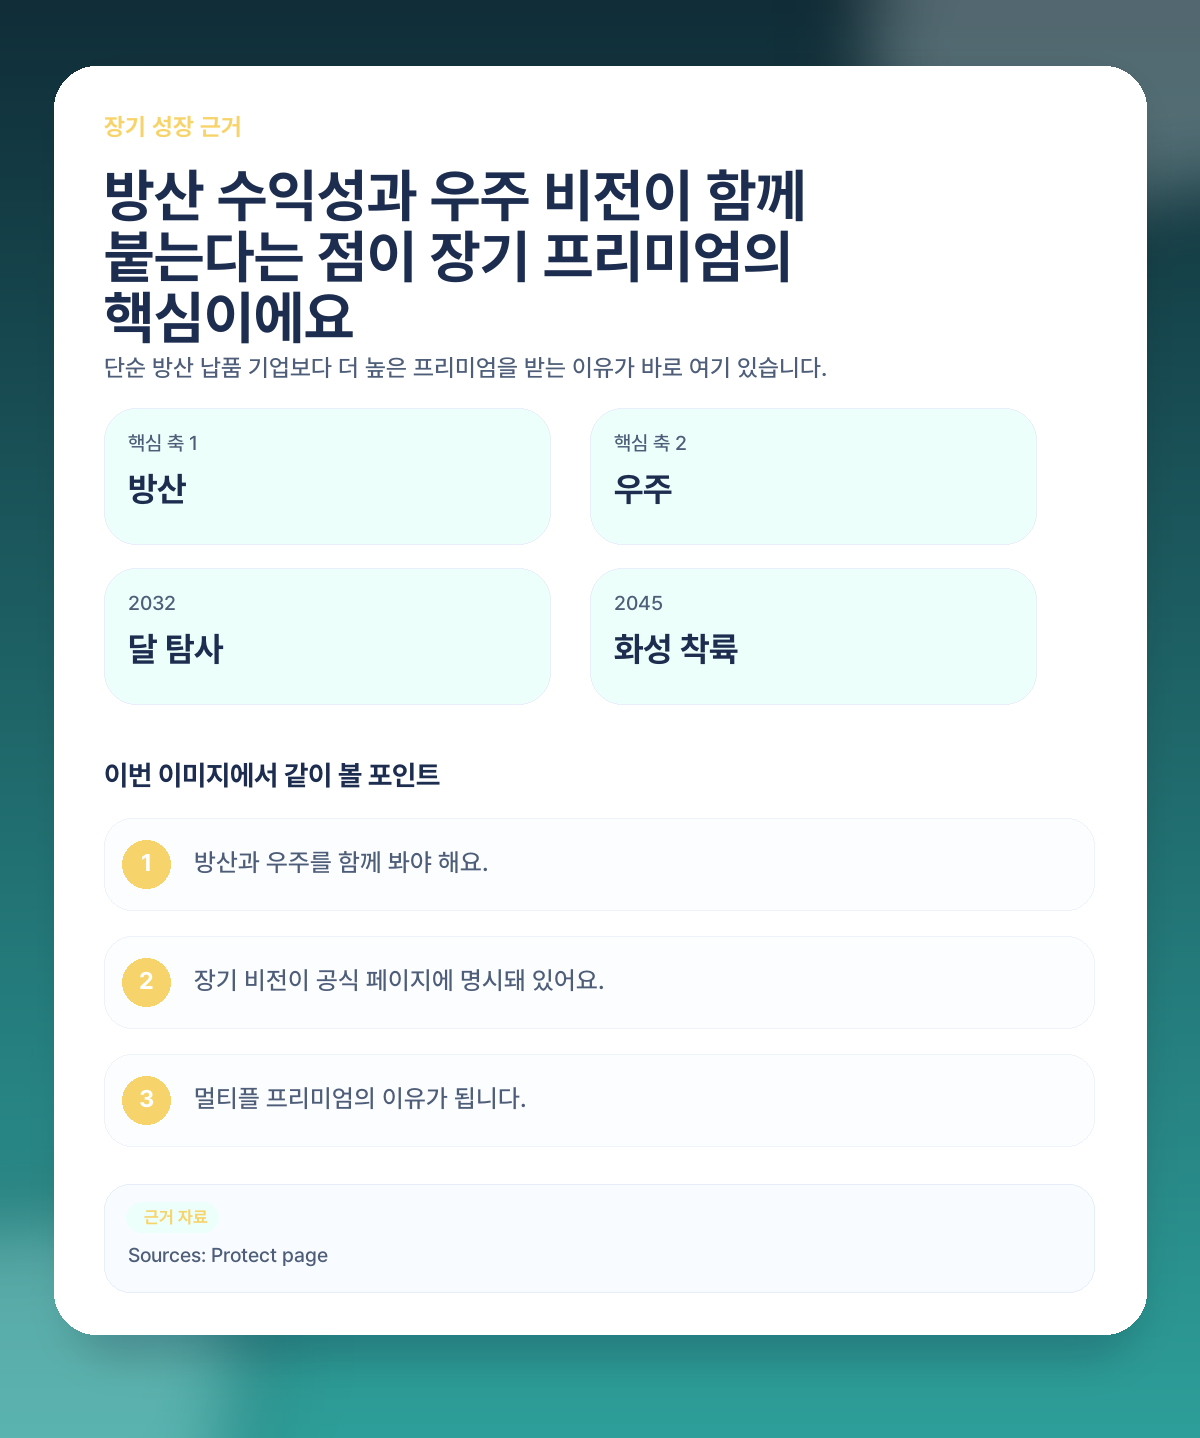
The long-run strength is that Hanwha Aerospace is not defense-only. Its official Protect page lays out a long-horizon direction spanning defense, green technology and space.
In particular, as the system-integration prime for Korea’s launch-vehicle advancement program, the company stresses a national space roadmap reaching a lunar mission in 2032 and a Mars landing in 2045. A narrative like that is precisely why a stock can command a higher multiple than a plain defense supplier.
In the end, the long-term premium rests on reading the company as both “defense that earns money now” and “space that could build value later.”
- Defense earnings and the space story run together.
- A long-term vision tied to national projects.
- Structural reasons to earn a premium beyond a simple order-book stock.
Pairs well with this article
Laptop Stand That Makes Long Sessions Easier
💬 One-line tip: raising your eye line just a little cuts intraday fatigue more than you would expect.
⚠️ The biggest short-term worries
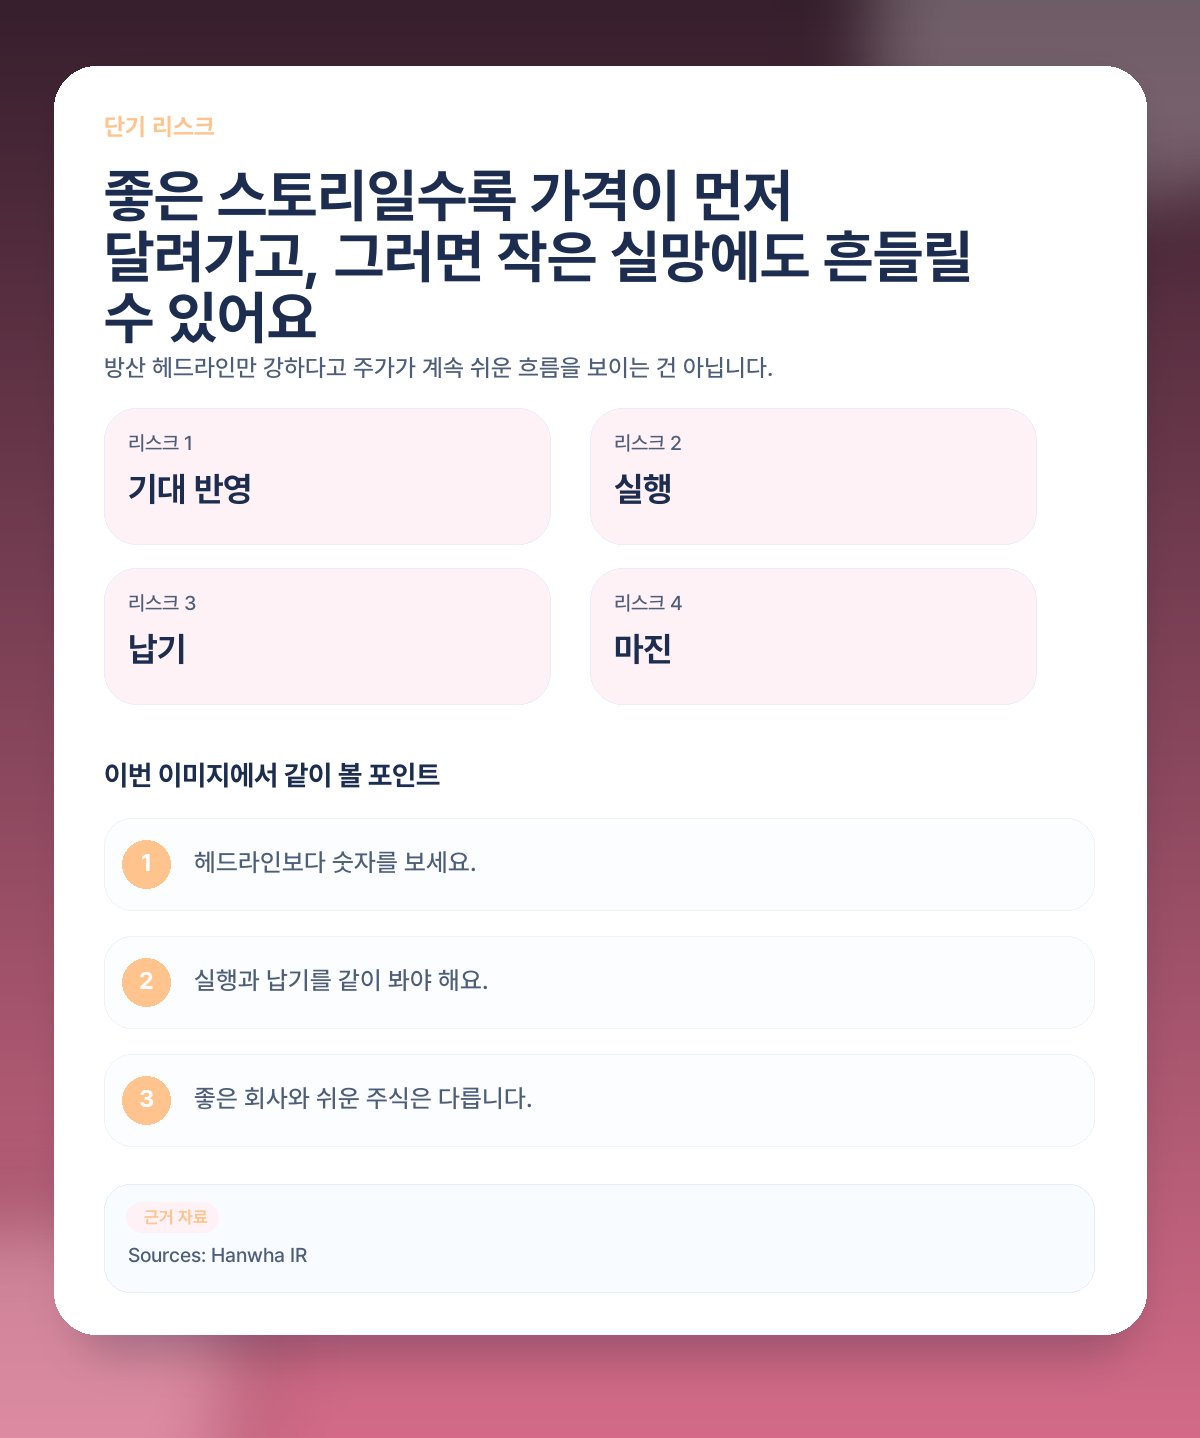
First, expectation pricing. The more the “defense super-cycle” phrase spreads, the more the market pre-loads bigger orders and bigger profits into the price — at which point even good news can fail to move the stock as much as you expected.
Second, execution risk. Defense is not just signed contracts: delivery schedules, production capacity, costs and the pace of overseas programs all have to be checked. Numbers can look great while actual cash flow and margins move differently.
Third, capex and valuation. Stocks with big long-term stories are always a tug-of-war between “great business” and “price too high.”
- The loftier the defense expectations, the bigger the potential disappointment.
- Watch execution, deliveries and margins together.
- Separate the long story from the short-term price.
✅ The realistic way to approach it now
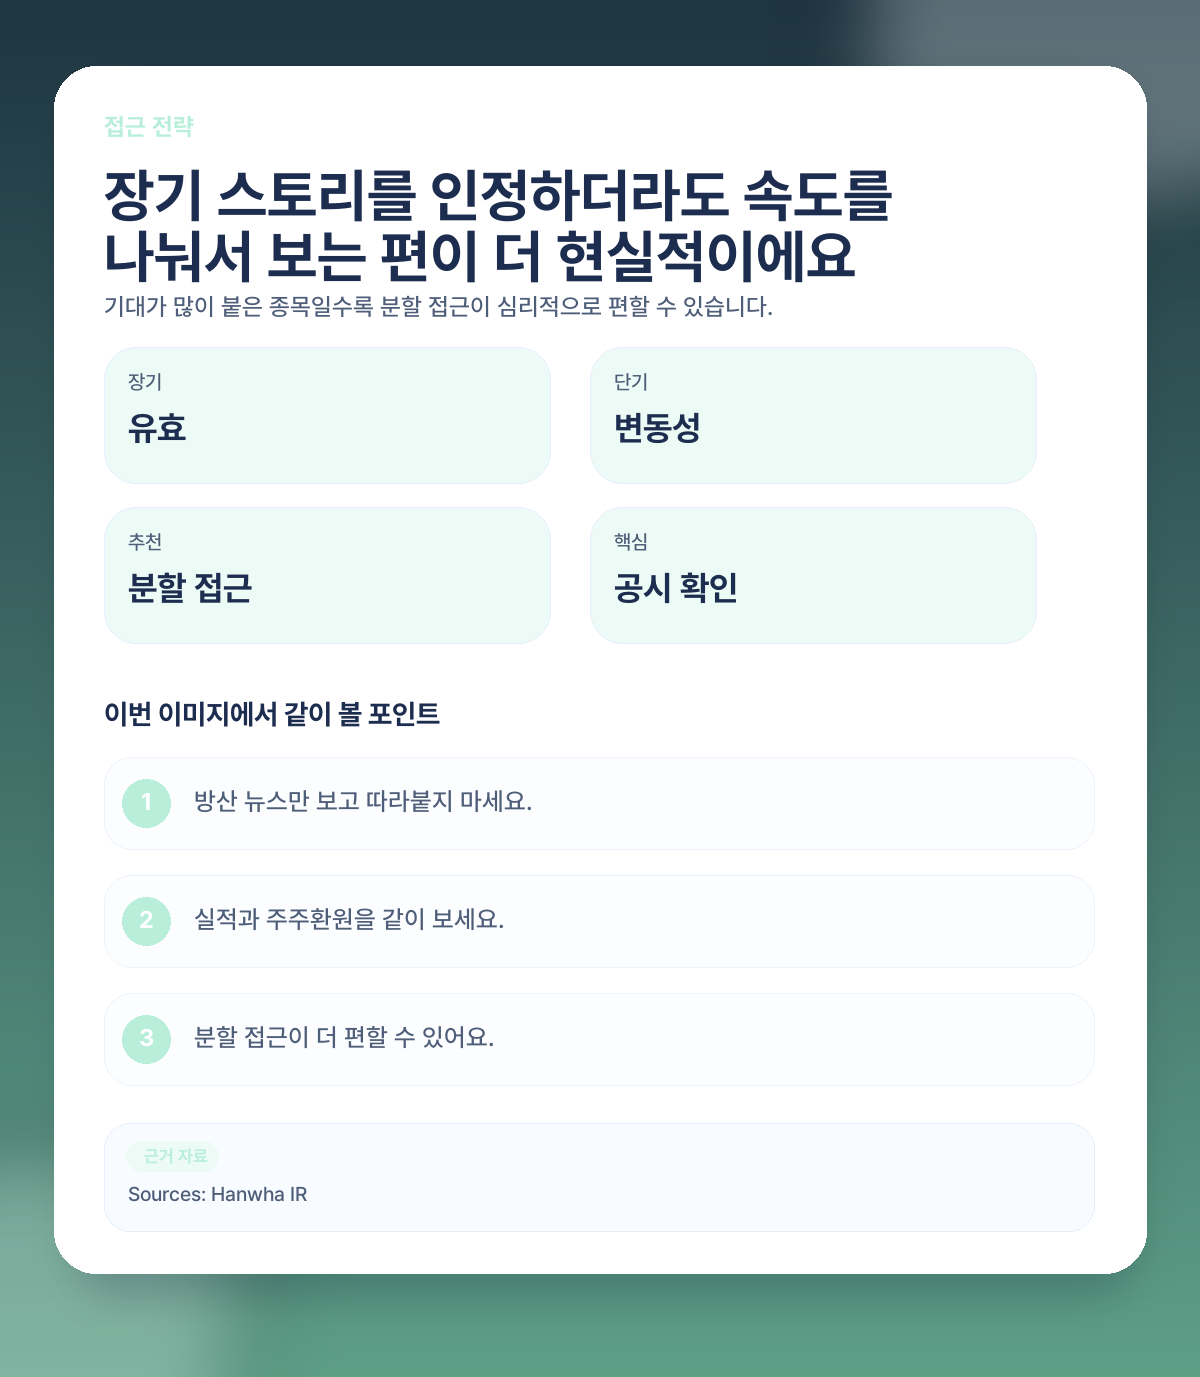
Even if you accept the long-term logic, Hanwha Aerospace suits a staged entry better than one large position — expectation-heavy stocks swing hardest.
Defense headlines always look bullish, but in practice the earnings releases and the actual progression of orders matter more. A habit of tracking filings and numbers fits this stock better than a vague feeling of “it’s good.”
In short: buying the long-term story is fine; handling the short-term price in calm tranches is the realistic part.
- Accept the story, but control the pace.
- Trust reported numbers over defense headlines.
- Tranches are easier on the nerves.
📌 Points to keep checking
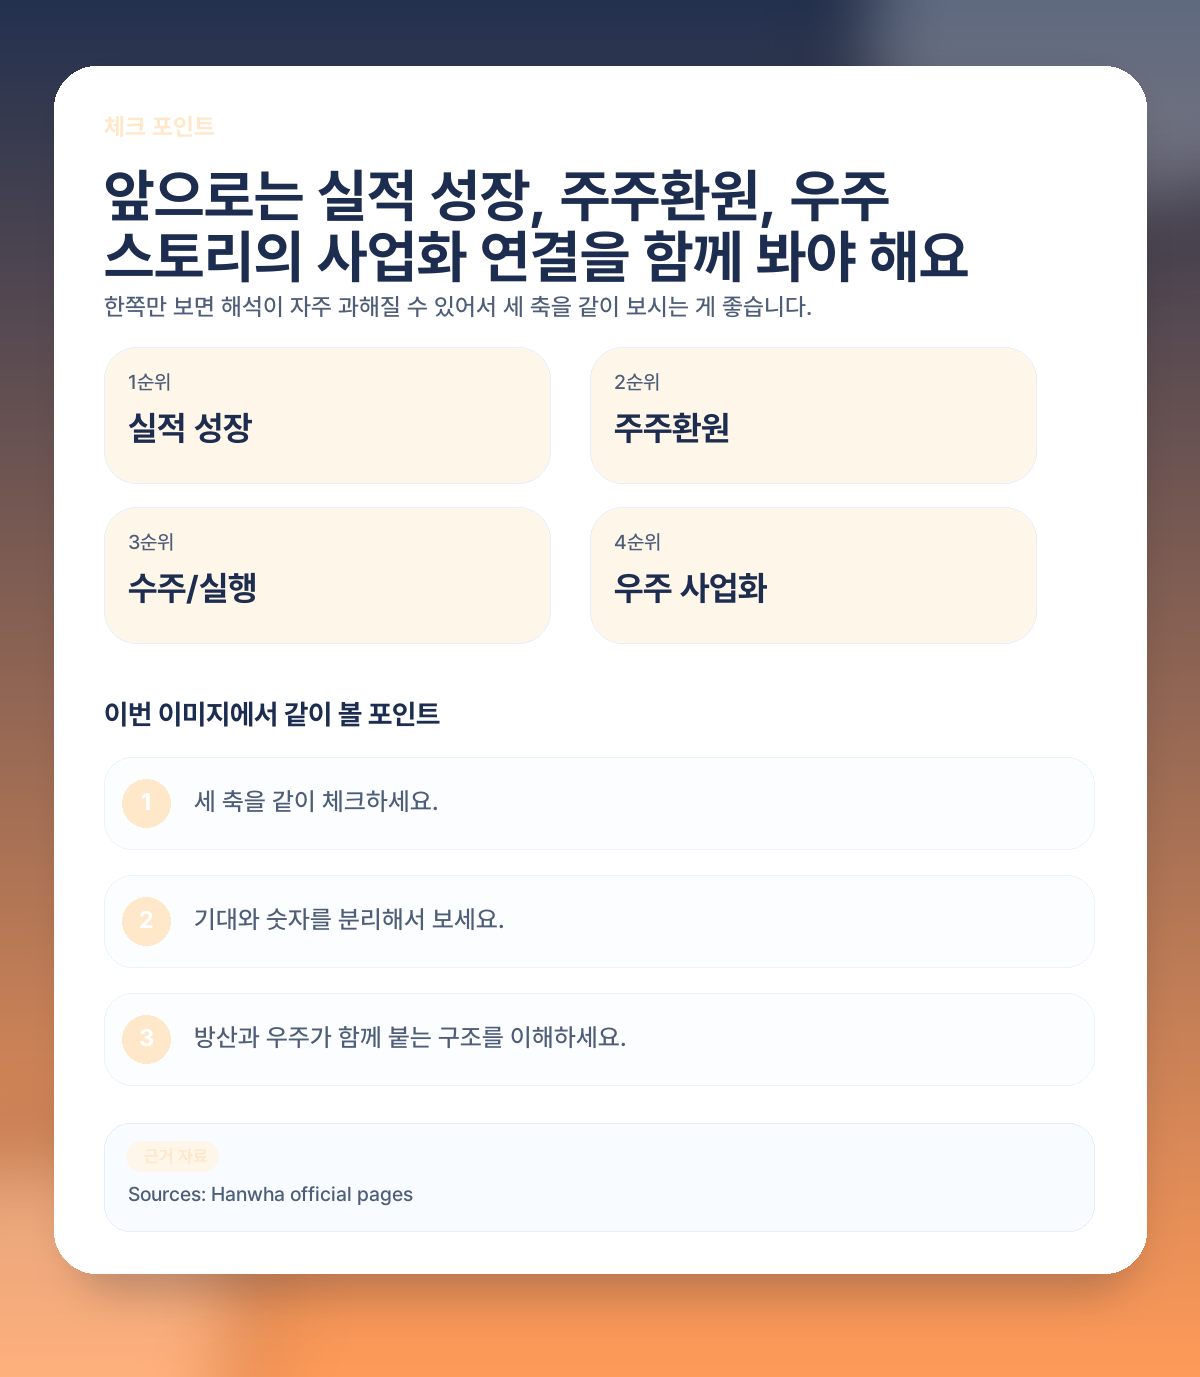
From here, track consolidated earnings growth, the expansion of overseas defense business, shareholder returns, and whether the space vision is actually converting into business results.
Hanwha Aerospace specifically fuses near-term earnings with long-term vision; watching only one side will keep distorting your read.
- Whether revenue and operating-profit growth persists
- Whether shareholder-return policy is actually followed through
- Whether the space story becomes concrete contracts and revenue
Pairs well with this article
Wireless Mouse Built for Notes and Chart Switching
💬 One-line tip: if you live between charts, notes, and browser tabs, the right basic tool is felt more than you’d think.
🙋 FAQ
❓ Is Hanwha Aerospace still a long-term candidate?
Yes — holding both the defense and space axes is genuinely attractive long term. Just remember that a matching amount of expectation can ride along.
❓ Has the defense super-cycle run its course?
The company’s own disclosures make the expansion intent clear. From a stock-price standpoint, the question is how much of the order pipeline is already priced in.
❓ Is the stock too expensive right now?
That concern is perfectly natural — which is why pacing entries in stages, even while accepting the long-term logic, is likely the safer route.
❓ Should I really count the space story?
Yes. The official Protect page has the company itself promoting a space vision alongside defense, so it belongs in any long-term-premium analysis.
🔎 Public sources referenced